Software 3.0 and the Quiet End of the SaaS Era
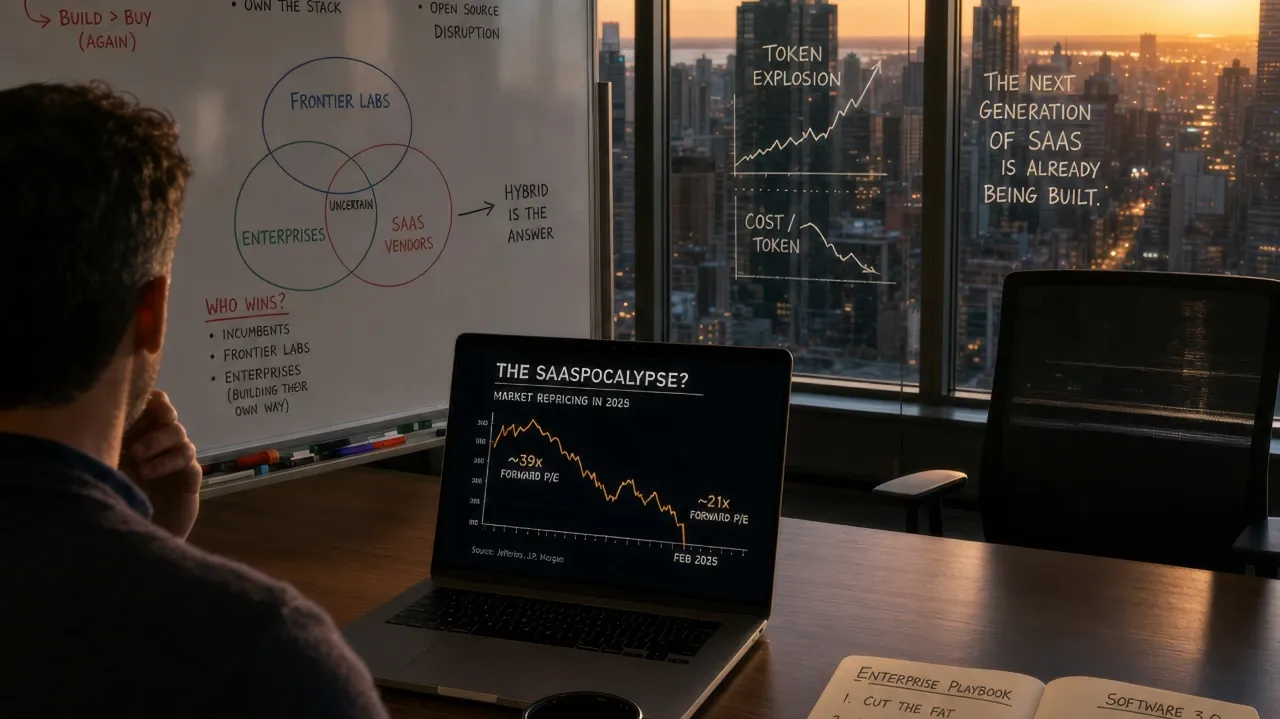
How the labs disrupting SaaS are quietly building the next generation of it.
I work at a SaaS company. I also work at a company that uses AI as a core part of its product. That puts me in a slightly uncomfortable seat for the conversation we are about to have, because the conversation is whether the entire business model that pays my salary is in the process of being unwound. Spoiler. I think the honest answer is yes. Just not in the way most people are claiming, and not for the reasons being shouted about on financial news.
Let me start somewhere safer and work back to the awkward bit.
Karpathy and the three eras of software
In June last year Andrej Karpathy gave a talk at Y Combinator’s AI Startup School where he carved the history of software into three eras. Software 1.0 is what most of us were trained on. You write explicit instructions in a programming language and the machine does precisely what you told it to. Software 2.0 is the neural network era. Instead of writing code, you curate data, design a model architecture, and let the optimiser find the weights. The code is the weights. The programmer’s job shifts from writing logic to shaping data.
Software 3.0 is what we are living through now. The programming language is English. The runtime is a large language model. You describe what you want and the model produces the behaviour. It can also produce Software 1.0 code, configure Software 2.0 systems, or just do the thing directly. Each generation eats the one before it, and Karpathy’s claim is that Software 3.0 is in the early stages of eating both 1.0 and 2.0 in the same way that 1.0 ate punched cards.
That is the framing. It is a useful framing. I am going to leave it there because the more interesting story is what happens when this framing collides with the way enterprise software is actually bought and sold.
The repricing event
Since the start of this year, roughly two trillion dollars of market value has evaporated from public software companies, with the largest single drawdown in early February when a frontier lab launched its enterprise agent product. Salesforce, Workday, Atlassian, ServiceNow, Snowflake, Cloudflare. Pick any large SaaS name and look at the chart. The financial press, in its usual restrained way, called it the SaaSpocalypse. The catalyst was an AI agent product capable of doing meaningful chunks of knowledge work without needing to log into any of the platforms those workers used to operate. Investors did the maths in roughly forty eight hours and concluded that per-seat licensing might not survive a world where the seat does the work itself.
Forward earnings multiples for software companies dropped from around thirty nine times to around twenty one times over a few months. Jefferies formalised the SaaSpocalypse label in its sector notes. JP Morgan called it the largest non-recessionary drawdown in software in over thirty years. This was not a mood swing. This was repricing.
I think the word SaaSpocalypse is wrong, though. It implies extinction. What is actually happening is something more measured and more interesting.
What is really happening
I know enterprises who have looked at their SaaS bill, realised they use about fifteen percent of three different platforms, and decided to build the fifteen percent themselves. They are not doing this because they hate their vendors. They are doing it because they suddenly can. The cost of building software has collapsed, and so has the time it takes to build it. A function that used to require a six person team and a year now takes a couple of engineers and a few weeks. That changes the buy versus build calculation for every line item on every CTO’s procurement spreadsheet.
This is not the death of SaaS. It is a reformation. Enterprises are doing three things at once and the press is collapsing them into one panicked story.
The first thing is a cull. Companies are taking a hard look at their subscription stack and asking which of these tools justify their cost given how much of them is actually used. Most knowledge workers have access to ten or fifteen platforms and seriously use three. The other twelve sit in their browser bookmarks like furniture they have learned to walk around. AI gives procurement teams the cover they have always wanted to terminate those contracts. The vendor cannot really argue, because the agent on the other side of the negotiation has already drafted three counter-proposals and modelled the renewal economics.
The second thing is internalisation. Where a SaaS product genuinely solves something, but the company only uses a sliver of its functionality, the calculation has changed. Building the sliver was not viable when it took a year. It is viable when it takes a fortnight. So they are building it. Not the whole platform, just the bit they need, glued to the data they already have, governed by their own controls.
The third thing is reformation of the engineering function itself. Companies that used to outsource entire categories of capability to SaaS vendors are quietly rebuilding internal engineering teams. Partly because they need to maintain the things they are now building. Partly because they are preparing for what comes next. Smart leadership teams have worked out that the next two years are going to involve a lot of weather, and the companies with strong internal engineering capability are going to ride it out better than the ones that hollowed themselves out during the SaaS boom and now own nothing but a stack of vendor contracts.
So yes, the SaaSpocalypse is real. But the story is not that SaaS dies. The story is that enterprises are using this moment to do the spring clean they have been putting off for a decade, and to rebuild the capability they will need for whatever comes after.
Who owns the infrastructure
There is a subtler problem sitting underneath all of this that nobody in the agent gold rush is keen to discuss. Software 3.0 is being built on infrastructure that nobody using it owns.
Look at where the frontier labs have moved over the last twelve months. They started by selling API access. Then they built coding agents. Then they built general purpose agent platforms. Now they are selling cloud-hosted enterprise agent suites that connect to your file systems, your communication tools, your customer data, your CRM, your document store, and your ticketing systems. They ship plug-ins so you can customise the agent for your team, your workflows, your branding, and your communication style. They offer managed agent platforms so you can deploy your own bespoke agents on their infrastructure rather than yours.
If that pattern looks familiar, it should. It is the SaaS playbook, run again from the bottom of the stack. The frontier labs are not just selling intelligence by the token. They are positioning themselves as the operating system of the agent era, with all the lock-in that implies.
The enterprise IP question this raises is awkward. When your agents are designed in someone else’s platform, customised through someone else’s plug-in framework, executed on someone else’s infrastructure, and improved by feedback loops that flow through someone else’s telemetry, what do you actually own? The prompt is yours. The data, mostly, is yours. But the operating model of your business, encoded in the agents and the plug-ins and the workflows, is now expressed in a language that only runs in one place. Migration is not impossible, but it is not free either. The patterns you build accumulate at multiple layers simultaneously. The model. The orchestration framework. The runtime. The connectors. The integrations. The plug-in catalogue. The institutional muscle memory of the people who use it daily.
Enterprises have spent twenty years building procurement frameworks specifically designed to stop any one vendor from becoming load bearing. Multi-cloud strategies. Vendor neutrality policies. Data portability clauses. Exit terms. The whole apparatus exists because the lessons of Oracle audits, Salesforce dependency, and AWS bill shock were expensive ones. And now, in their rush to deploy AI before their competitors do, many of the same enterprises are signing up to a far more total form of dependency without applying any of those lessons. The agent platform is not just a piece of software. It is the system through which work happens.
The IP problem is sharper still. Outputs generated by agents in cloud-hosted platforms sit in a legal grey zone that has not been resolved. Some vendors offer indemnification against intellectual property claims. Some do not. Most enterprise procurement teams have not yet worked out which questions to ask, let alone what good answers look like. And the more an enterprise pours its proprietary data, processes, and decision logic into a vendor-hosted agent, the harder it becomes to argue that the resulting outputs are unambiguously its own.
This matters for the SaaSpocalypse story because it changes who the disruptor actually is. The narrative says SaaS vendors are losing to AI agents. The reality is that the SaaS vendors are losing to a small number of frontier labs who are building the next generation of SaaS, with deeper integration, broader scope, and more lock-in than anything that came before. The repricing of incumbent SaaS is not the end of the model. It is a regime change. The new tenants are bigger and they have moved in upstairs.
The token problem
Here is where it gets uncomfortable for the frontier labs.
Software 3.0 has a unit economics problem that nobody likes talking about. Every interaction burns tokens. Every agent loop burns more. An agent that handles a customer support ticket end to end might consume tens of thousands of tokens. An agent that drafts a contract, reviews it against precedent, and negotiates revisions can chew through hundreds of thousands. Multiply that by the volume of work an enterprise actually does and the bills start to look frightening.
The frontier labs have so far absorbed a lot of this through aggressive pricing and the assumption that costs will keep dropping. They have been right about the cost curve. Inference costs per token have fallen dramatically. But the volume of tokens being consumed has risen even faster, and the agent era has only just started. The work an agent does is fundamentally token hungry in a way that a human clicking around a SaaS interface is not. We are heading into a token explosion, and the question nobody has a good answer to is whether the cost curve can outrun the volume curve.
If it cannot, then Software 3.0 hits an economic ceiling. Enterprises will stop deploying agents at the rate the hype cycle suggests, not because the technology fails but because the bill becomes unjustifiable. The SaaSpocalypse becomes self-limiting. The big SaaS vendors get a reprieve they did not earn, and a lot of agent startups discover that their margins were imaginary.
For Software 3.0 to actually deliver on its promise, the frontier labs need to do something more than incremental optimisation. They need a step change. Either a meaningful architectural shift away from brute force autoregressive generation, or a step function reduction in cost per useful unit of work, or new model designs that get more done with fewer tokens. The labs know this. The question is whether they can ship it before the unit economics catch up with them.
The open source problem
And then there is the other problem the frontier labs are trying not to look at directly.
Open weight models are no longer trailing far behind the frontier. Kimi K2.6, DeepSeek V4, GLM-5.1, Qwen 3.6. These are not curiosities. They are running real workloads at real companies, on benchmarks that put them within a few percentage points of the proprietary leaders for coding and reasoning tasks. They ship under permissive licences. They can be self-hosted on enterprise hardware. They can be fine-tuned on private data without that data ever leaving the building.
For an enterprise staring at a frontier API bill that scales with the token explosion, the procurement question is starting to look very different. If an open weight model can match the leading proprietary models on most benchmarks for a fraction of the cost, with full data residency and no vendor lock-in, what exactly is the frontier API premium buying you? Better quality on the long tail of hard problems, yes. Faster updates, yes. A more polished experience, yes. But for the bulk of agent work, which is repetitive and well-scoped and runs at high volume, the answer for many enterprises is going to be that the premium is not worth paying for every token.
This is the bind the frontier labs are in. Their margin depends on enterprises being unable to escape. Open weights are the escape route. And the moment enterprises adopt a hybrid posture, where the cheap and predictable workloads run on self-hosted open models and only the genuinely difficult problems hit the frontier API, the frontier labs lose the volume that funds their next training run. Which means they need that step change in efficiency to justify the premium. Which is the same problem from a different angle.
Where this leaves us
The SaaSpocalypse, as branded, is a misreading of what is actually happening. Enterprises are not abandoning software. They are abandoning the assumption that software has to be bought from someone else. The combination of plummeting build costs, AI assisted development, and open weight models is letting them take back ground that the SaaS era took away. The cull, the internalisation, and the reformation of internal engineering are all happening at once, and the public market repricing is the visible tremor of a much larger underground shift.
Software 3.0 is real, and it is happening, but it has not yet earned its place. The token economics do not yet work for the agentic future its proponents describe. Open weight models are eating into the frontier labs’ premium from below. And the frontier labs themselves are building the next generation of SaaS-style lock-in from above, hoping that enterprises move too quickly to notice they are signing up for a deeper dependency than the one they are escaping.
These three forces are pulling in different directions at the same time. The token explosion punishes any enterprise that commits fully to frontier APIs. The open source ecosystem offers an exit route that gets more credible every quarter. The cloud-hosted agent platforms offer a level of capability that is hard to match from a self-hosted stack, but at the cost of strategic dependence on the lab providing them. Enterprises that pick one of these three forces and ignore the others will get this wrong. The ones who get it right will run hybrid, treating the agent runtime as a portfolio decision rather than a vendor relationship.
The frontier labs need to deliver the step change in efficiency that justifies their premium, before open weights and self-hosting close the gap entirely. The SaaS vendors need to find a reason to exist that does not depend on per-seat lock-in. And the rest of us, the people who actually have to make this work inside real companies, need to stop waiting for the dust to settle and start building for the version of the industry that will exist in three years rather than the one we grew up in.
I am writing this from inside a SaaS company that uses AI. That seat is not as uncomfortable as I made it sound at the start. It is just the seat where you can see all sides of the argument at once. And from here, the view is that the industry is not ending. It is being remade.
The interesting question is whether the people remaking it will be the incumbents, the frontier labs, or the enterprises themselves quietly building their own way out of both.
Originally published on linkedin.com.